Beyond the Claim: How Technology and Trust Are Reshaping India’s Insurance Grievance Economy?
India’s insurance story is often told through the lens of penetration, premiums and policies sold.
But there is another side to that story—what happens when a policyholder actually needs the insurance to work?
A claim is delayed. A claim is rejected. A policy was allegedly mis-sold. An exclusion was not understood. A family discovers that the coverage it believed it had does not necessarily translate into the protection it expected.
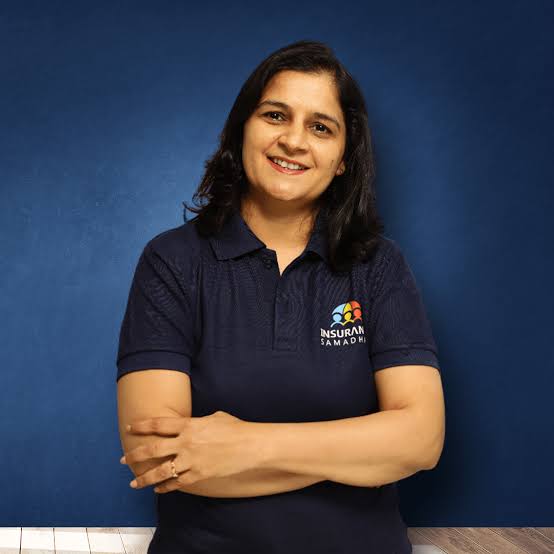
For Shilpa Arora, Co-Founder and COO of Insurance Samadhan, this is where the real test of India’s insurance ecosystem begins.
Arora’s journey into insurance grievance redressal was shaped by years of experience across insurance and customer service. At Max New York Life, she encountered policyholders struggling to navigate complex insurance products and claims. One case involving an elderly policyholder who had allegedly been mis-sold multiple policies became a turning point and eventually contributed to the creation of Insurance Samadhan.
Founded in 2018, Insurance Samadhan has evolved into a technology-enabled platform focused on helping policyholders address insurance grievances across health, life and general insurance. The company has reported handling more than 20,000 grievance cases since inception.
The timing is significant. India’s insurance ecosystem is expanding, while the grievance architecture is under increasing pressure. IRDAI’s Bima Bharosa provides a centralised mechanism through which policyholders can register and track complaints, while unresolved or unsatisfactory matters can move through further escalation channels, including the Insurance Ombudsman.
In this exclusive conversation with CXO Herald, Shilpa Arora discusses the hidden friction in India’s insurance journey, why claim rejection and mis-selling remain persistent challenges, how technology can democratise access to grievance redressal, what the regulatory ecosystem needs to evolve, and where Insurance Samadhan sees its next phase of growth.
Origin & Problem Statement
1. What was the core problem in India’s insurance ecosystem that led you to build Insurance Samadhan?
A: India has done well on selling insurance, but very little was built to help a policyholder once something goes wrong -a claim gets delayed, rejected, or a policy was mis-sold in the first place. My co-founders and I had spent close to three decades between us across insurance and pharma, and we kept seeing the same pattern: genuine policyholders who didn’t know where to go or how to fight a rejection. That gap between buying a policy and actually being served when you need it most is what led the five of us to start Insurance Samadhan in 2018.
2. What are the most common grievances policyholders approach Insurance Samadhan with today?
A: The bulk of what we see falls into three buckets: claim rejections in health and life insurance, mis-selling -where a policy was sold as a fixed deposit or guaranteed-return product -and delayed or short settlements. Within claims, non-disclosure of prior conditions and disputes over pre-existing-disease waiting periods are especially common, particularly on ported policies, where more than half of rejections trace back to exactly these two reasons.
3. Why do genuine policyholders still struggle to get fair resolution from insurers despite the existing grievance-redressal framework?
A: The framework -insurer grievance cells, the Ombudsman, IRDAI’s channels -does exist, but most policyholders don’t know it exists, don’t know how to build a case, and don’t have the time or expertise to counter an insurer’s rejection letter with the right policy clauses and precedents. It’s an information and expertise gap more than a policy gap, and that’s exactly the space we operate in.
4. How significant is the gap between insurance penetration and effective insurance servicing in India?
A: It’s significant, and it’s arguably a bigger problem than penetration itself. The industry and regulator have rightly focused a lot of energy on getting more people insured, but comparatively little has gone into the post-sale journey -servicing, claims support, and grievance handling. As more first-time buyers enter the market, that servicing gap becomes more visible, which is part of why we’ve seen grievance volumes rise.
Technology & Differentiation
5. How is technology helping simplify insurance grievance resolution involving documentation, policy interpretation and regulatory processes?
A: Our platform -Polifyx -lets a policyholder store their policy documents digitally, and we use AI/ML to read the policy and flag issues before they even become a claim problem, like a non-disclosure risk or an incorrect nominee. When a grievance does come in, technology helps us map the case against the right regulatory clauses and precedent, and route it through the right channel -insurer, Ombudsman, IRDAI, or consumer forum -much faster than a purely manual process would.
6. How much of your grievance assessment and case-management process is now technology-driven?
A A large and growing part of it. Initial case evaluation runs against a structured set of roughly 80–100 parameters that our algorithm checks, and that parameter set keeps expanding as our models learn from more cases. That said, we deliberately keep experienced human case managers in the loop for judgment calls and for actually representing the policyholder -this isn’t a fully automated process, nor should it be.
7. Are you using AI/ML to identify patterns in rejected claims, mis-selling, delayed settlements or other systemic issues?
A: Insurance Samadhan is increasingly using AI/ML not just for case triage, but to identify patterns across our structured grievance data. This includes rejection patterns, insurer responses, resolution pathways, policy/document deficiencies and mis-selling signals. The longer-term objective is to turn individual grievance journeys into ecosystem-level insurance outcome intelligence.
8. What is difficult about building technology for insurance grievances compared with a conventional fintech or insurtech platform?
A: Most insurtech platforms are built for a relatively standardised, forward-looking transaction -buying a policy. We’re working backwards from a dispute, which means every case involves messy, non-standard documentation, differing policy wording across insurers, and judgment calls that don’t reduce neatly to a rule. Building technology that can handle that variability, without losing the nuance a human case manager would catch, is the hard part.
9. How do you ensure automation does not compromise the human element required in sensitive insurance disputes?
A: We treat technology as something that supports our case managers, not replaces them. A claim rejection is often tied to a genuinely stressful moment in someone’s life -a hospitalisation, a death in the family -and that needs empathy, not just an algorithmic output. So automation handles the heavy lifting on documentation, pattern-matching and case tracking, while every case still has a human owner who talks to the policyholder.
Market Opportunity
10. How large do you believe the addressable market for insurance grievance-resolution services could become in India?
A: According to IRDAI’s Annual Report 2024-25, grievances are rising year on year -up to roughly 2,57,790 in FY24-25, a 20% jump over the prior year. The same report notes that insurance penetration is still climbing off a low base of just 3.7%, about half the world average. Given this, I’d expect the addressable market to keep expanding for the next several years before any moderation sets in. It’s a market shaped directly by how fast the industry sells policies versus how fast it fixes its servicing gaps.
11. Which segment presents the biggest opportunity -health, life, motor, general insurance or corporate insurance?
A: Health insurance is currently the biggest source of disputes we see, driven by rising premiums, cashless denials and claim rejections. Life insurance mis-selling -policies sold as investment or guaranteed-return products -is a close second. Motor and general insurance matter too, but health and life are where the volume and the emotional stakes are highest today.
12. With increasing insurance awareness and digital adoption, do you expect grievance volumes to increase before they eventually decline?
A: Yes. As more people become aware that they can dispute a rejection instead of accepting it, and as digital channels make it easier to file a complaint, I’d expect reported grievance volumes to keep rising in the near term. A real decline would only follow once insurers tighten their sales and claims practices and the regulatory infrastructure -more ombudsmen, faster digital redress -catches up.
13. Is Insurance Samadhan primarily consumer-facing, or do you see opportunities in B2B partnerships with insurers, brokers, banks, TPAs and other financial institutions?
A: Insurance Samadhan operates across both consumer and enterprise channels. While our platform directly serves policyholders, we also work across the insurance and financial-services ecosystem through technology, servicing and distribution partnerships. Our platform is designed to integrate with existing workflows rather than replace insurers, advisors or other ecosystem participants.
14. Could grievance data become an important source of intelligence for improving underwriting, claims management and customer experience?
A: Absolutely. We’re sitting on thousands of resolved, well-documented grievances that show exactly where products, claims processes and customer servicing break down. In aggregated form, that’s exactly the kind of intelligence insurers and regulators could use to improve underwriting and claims design rather than just reacting to complaints after they happen.
Challenges
15. What are the biggest challenges faced by a technology company operating at the intersection of insurance, regulation and consumer protection?
A: You’re building for three audiences at once -the policyholder, the insurer, and the regulator -and each has different incentives. Add to that the sensitivity of the personal and medical data we handle, and the need to stay current with regulatory processes that themselves keep evolving, and it’s a genuinely harder build than a typical consumer tech product.
16. How difficult is it to create consumer awareness when many policyholders do not know their escalation options?
A: It’s one of our biggest ongoing efforts. Most people believe a claim rejection is the end of the road, when in reality they can escalate to the insurer’s own grievance cell, to the ombudsman, to IRDAI’s Bima Bharosa portal, or to a consumer forum. Reaching people in semi-urban markets, and explaining this in plain language rather than regulatory jargon, takes sustained work -it isn’t a one-time awareness campaign.
17. Does the insurance industry have sufficient transparency around claim rejection and policy servicing?
A: There’s room to improve. Rejection letters and policy documents are often written in language that’s hard for a lay policyholder to interpret, and the reasons for rejection aren’t always communicated as clearly as they could be. Greater standardisation and simpler communication at the point of rejection would go a long way.
18. What are the biggest operational challenges in handling large volumes of individual grievances?
A: Every case tells its own story -a different insurer, different policy language, its own set of documentation gaps. Scaling that kind of work, without letting quality or turnaround time slip, is the real challenge. That’s why we’ve put serious investment into technology that standardises what’s standardisable, while making sure experienced people stay in control of everything that isn’t.
19. How do you balance consumer advocacy with maintaining constructive relationships with insurance companies?
A: By being selective and evidence-based rather than adversarial by default. We only bring forward cases we’re confident are genuine, well-documented and fairly presented, which is exactly why insurers engage with us productively -they know we’re not filing indiscriminately. That credibility is what lets us advocate hard for a policyholder without burning the relationship we need for the next case.
Regulatory & Policy Environment
20. How do you assess the evolution of India’s insurance grievance-redressal ecosystem under IRDAI?
A: IRDAI has made real progress -initiatives like Bima Bharosa and Bima Sugam, and tighter norms around mis-selling and surrender values, show the regulator is paying attention to the servicing side, not just market growth. But the on-ground infrastructure hasn’t kept pace: with only 18 ombudsmen nationwide, policyholders in major cities can still wait months to a year for a hearing.
21. What regulatory changes would significantly improve consumer protection without unnecessarily increasing compliance burdens?
A: More ombudsman capacity and regional benches would probably have the single biggest impact, since that’s where the current bottleneck is. Standardising how insurers communicate a claim rejection -in plain language, with a clear next-step for escalation -would also protect consumers without adding meaningful compliance cost for insurers who are already handling claims properly.
22. Does India need a more integrated digital architecture connecting policyholders, insurers, intermediaries, TPAs and grievance-redressal mechanisms?
A: Yes. Right now, a policyholder’s information and case history often lives in silos across the insurer, the TPA and the grievance body, which slows everything down. A shared digital architecture connecting all of these would cut resolution times significantly and give the regulator much better visibility into where problems are recurring.
23. Could AI-powered grievance analytics help regulators identify systemic issues across insurance companies?
A: Definitely. Right now, most regulatory attention is case-by-case. Analytics run across the pattern of complaints -which insurers, which products, which rejection reasons recur most -could help IRDAI spot systemic issues proactively, rather than waiting for enough individual complaints to pile up before acting.
Business Model & Scalability
24. How does Insurance Samadhan make money, and how do you maintain transparency and consumer trust within that model?
A: We operate primarily on an outcome-linked model: a registration fee once we accept a case, followed by a success fee when a grievance is successfully resolved. We also have B2B offerings across the insurance ecosystem. The underlying principle is that our incentives should remain aligned with delivering a meaningful outcome for the policyholder.
25. What have been the biggest lessons from scaling a technology-enabled grievance-resolution business?
A: The biggest lesson is that discipline in case selection matters more than raw volume -taking on only the genuine, well-evidenced cases is what keeps our success rate high and our relationships with insurers workable. The other big lesson is that technology and human expertise have to scale together; neither one alone gets a family their claim back.
26. Which metrics are most important -cases resolved, settlement value, turnaround time, customer satisfaction or something else?
A: We look at all of them together rather than any single number -cases resolved and our success rate, total settlement value recovered for policyholders, turnaround time per case, and customer satisfaction. But if I had to pick the one that matters most to how I judge our own performance, it’s the success rate on genuine cases, because that’s the clearest proxy for whether we’re actually delivering on our promise.
27. How do you maintain quality as case volumes grow exponentially?
A: Standardising the assessment process through our parameter-based model and continuously training it on new cases lets us maintain consistency even as volumes rise. On the people side, we invest in training our case managers on evolving regulations and insurer practices, so quality doesn’t dilute as the team scales.
Growth Plans
28. What are Insurance Samadhan’s growth priorities for the next three to five years?
A: Our focus is to scale Insurance Samadhan into a technology platform for the post-issuance insurance lifecycle. Key priorities include expanding the Polifyx platform and digital customer/partner experience; scaling our presence across India and subsequently international markets, particularly Asia, the Middle East and Africa; building deeper AI-led capabilities across policy intelligence, grievance resolution and insurance outcome intelligence; and expanding our technology and enterprise offerings across the wider insurance ecosystem.
29. Are you looking at expanding beyond insurance grievances into broader financial-consumer protection?
A: Our current focus remains firmly on insurance and the post-issuance insurance lifecycle. We are focused on building depth within insurance before considering adjacent categories.
30. What role will AI play in your next phase of growth?
A: AI will increasingly become the intelligence and automation layer across our platform. We are using it for policy understanding, document intelligence, case classification, resolution strategy, automated drafting and escalation workflows. Over time, we aim to use our proprietary insurance-outcome data to make resolution more predictive and scalable.
31. Are you looking at strategic partnerships with banks, hospitals, employers, fintechs, insurance brokers or global technology companies?
A: Yes, we see Insurance Samadhan as an ecosystem platform and are building partnerships across insurance, financial services and healthcare. Our existing and planned ecosystem includes insurers, advisors, wealth managers, fintechs, corporates, hospitals and other distribution and technology partners.
32. Do you see opportunities to take the Insurance Samadhan model beyond India?
A: India remains our primary focus in the near term because regulation and grievance processes are highly market-specific. Over the longer term, however, we see potential in other emerging insurance markets where the same underlying problem exists – insurance distribution can scale faster than the systems built to service policyholders after the sale.
33. Are you considering institutional investment or strategic capital to accelerate expansion?
A: Insurance Samadhan has raised ₹34+ crore from institutional investors, family offices and domain-expert angels since 2018. We are looking for strategic investors that can add value.
Closing Questions
34. If you could change one thing about India’s insurance ecosystem today, what would it be?
A: I’d want faster, simpler grievance redress -in concrete terms, that means more ombudsman capacity so a policyholder in a major city isn’t waiting months to a year just to get a hearing. Everything else we’d want to fix follows from fixing that bottleneck first.
35. What is the biggest misconception Indian consumers have about insurance claims and policyholder rights?
A: That a claim rejection is final. In reality, a policyholder can escalate to the insurer’s own grievance cell, to the ombudsman, to IRDAI’s Bima Bharosa portal, or to a consumer forum -most people simply don’t know these options exist, so they accept a rejection they didn’t have to accept.
36. In five years, what would success look like for Insurance Samadhan -not just as a company, but in terms of changing the way Indians experience insurance?
A: Success would be Insurance Samadhan becoming a broader trust layer for the industry, not just a place people come to after something has gone wrong. If we’re doing our job well, more issues get caught and corrected before they turn into a full-blown grievance, and the word ‘grievance’ becomes a little less common in how Indians talk about their insurance.
37. Can Insurance Samadhan evolve from being a grievance-resolution platform into an intelligence layer for India’s entire insurance ecosystem?
A: I believe so. We already sit on a large, real-world dataset of documented grievances across products and states. The evolution is in offering that data, in an aggregated and anonymised form, back to insurers and regulators so it becomes a tool for improving products and processes -not just a record of complaints.
Editor’s High-Impact Question
“Insurance Samadhan sits on a unique data layer -thousands of real consumer grievances revealing where insurance products, claims processes and customer servicing are failing. Do you see this data becoming a strategic asset that can help insurers and regulators move from merely resolving grievances to actually preventing them?”
A: Yes, and that’s really the direction we want to take the company. Every resolved case tells us something about where a product, a sales process or a servicing step failed -multiplied across thousands of cases, that becomes a genuine early-warning system. The opportunity ahead isn’t just resolving more grievances faster; it’s using that pattern data, responsibly and in aggregate, to help insurers and regulators fix the underlying issues before they reach the next policyholder.
The Bigger Picture
India’s insurance opportunity is enormous—but the next phase of growth will be measured by more than policies sold and premiums collected.
It will be measured by trust at the moment of truth.
As technology makes insurance distribution faster and more accessible, grievance redressal will become an increasingly important part of the industry’s customer proposition.
For Shilpa Arora, that is where the opportunity lies: not merely in helping policyholders fight rejected claims, but in using technology, data and financial literacy to make the insurance journey itself more transparent.
The future of Indian insurance, therefore, may not simply belong to the companies that sell the most policies.
It may belong to the organisations that make consumers believe in the promise behind those policies.