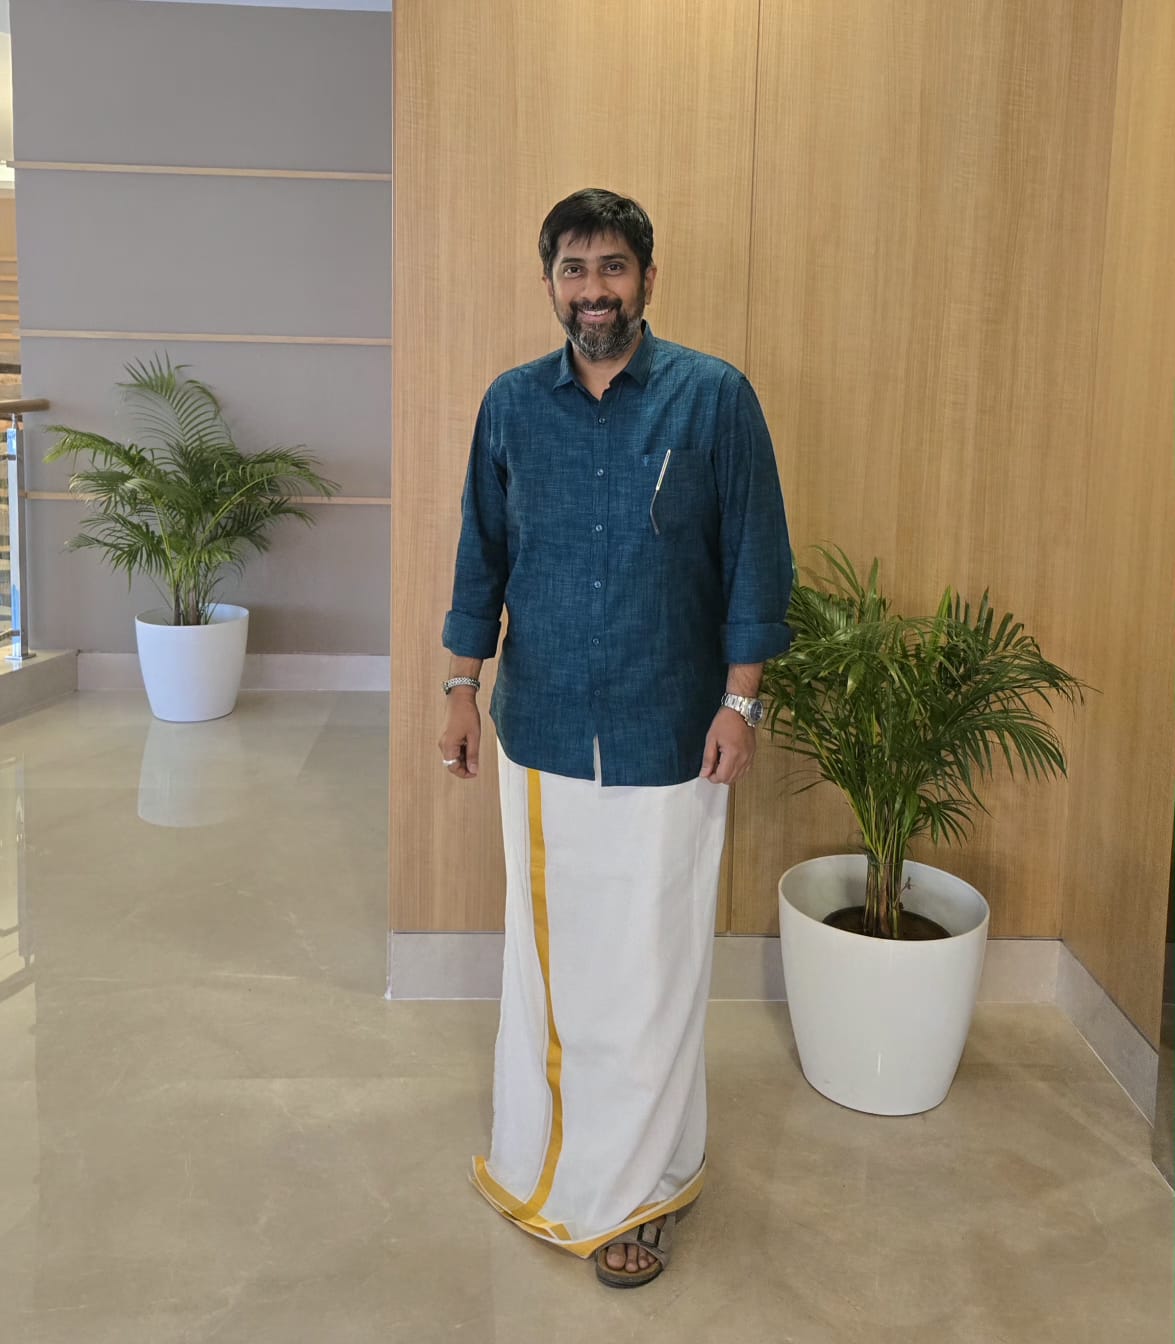
From leading complex international projects to evaluating ventures, the former Garuda Aerospace executive Mr. Madhu GN is building a distinctive approach to startup investment and enterprise value creation.
By CXOherald Editorial Team
From Engineering and Global Business to Venture Architecture
In the world of startups, entrepreneurs are celebrated for ambition, investors are admired for their capital, and valuations often dominate headlines. Yet, beneath the excitement of funding announcements and rapid expansion lies a more fundamental question: How many businesses are genuinely built to survive, scale and create enduring value?
For G. N. Madhu, a venture architect, strategic investment professional and angel investor, the answer begins with discipline rather than hype.
With more than two decades of cross-border professional experience spanning India, the Middle East and Europe, Madhu brings together technical engineering, corporate strategy, investment advisory and business transformation. Having previously served as Chief Growth Officer and Investment Officer at Garuda Aerospace Limited, he is now pursuing his journey as a serial startup investor, working with entrepreneurs to strengthen business models, improve operational discipline and prepare ventures for institutional capital.
His approach challenges several assumptions associated with contemporary startup culture. Instead of prioritising valuations, aggressive expansion and headline-grabbing fundraising, he emphasises operational integrity, capital efficiency, founder quality and long-term enterprise value.
He calls this approach the “Anti-Entrepreneur” philosophy—a framework designed not to discourage entrepreneurship, but to challenge the behaviours that can undermine otherwise promising businesses. For Madhu, the objective is straightforward: build companies that can justify their valuations through execution, commercial performance and sustainable growth.
The Capital Markets Perspective: Learning from 500+ Investor Connections
One of the most significant claims in Madhu’s executive profile is his engagement with more than 500 venture capital and private equity firms across different sectors.
Such exposure, when combined with sustained investment analysis, can offer insight into how institutional investors assess opportunities, evaluate risk and determine whether a company is ready for investment.
Fundraising is often misunderstood by founders as a presentation exercise. A compelling pitch deck and an attractive market narrative can open doors, but institutional investment decisions generally require much more. Investors need to understand the business model, revenue quality, competitive advantage, management capability, governance standards, capital requirements and potential investment returns.
Through his engagement with the investment community, Madhu has developed a focus on connecting the realities of business execution with the expectations of capital providers. For founders, this means preparing for difficult questions before entering fundraising discussions: Can the company demonstrate customer demand? Are its margins sustainable? What is the cost of acquiring customers? How much additional capital will be required? What milestones will the proposed funding achieve?
The central lesson is that capital should follow credible business fundamentals, not substitute for them.
Evaluating Startups: Finding the Founder Behind the Opportunity
Madhu’s profile also states that he has evaluated more than 2,000 startups and growth-stage enterprises annually over the past five years. This volume of exposure, if confirmed, represents a substantial opportunity to observe recurring patterns across business models, industries and stages of development.
Some startups fail because they build products without validating customer demand. Others acquire customers but struggle to generate sustainable margins. Some have strong technology but weak distribution, while others possess promising commercial opportunities but lack the management systems required to scale.
Madhu emphasises the importance of identifying the right founder—the individual capable of turning an opportunity into a functioning enterprise. In investment circles, this is sometimes described as backing the “jockey” rather than focusing exclusively on the “horse.” It means assessing a founder’s judgement, adaptability, integrity, execution capability and understanding of the market.
Founder quality must still be assessed alongside market demand and business economics. A strong founder cannot indefinitely compensate for a weak market or an unsustainable model. Effective venture evaluation requires a balanced assessment of people, products, markets and financial realities.
The “Anti-Entrepreneur” Philosophy: A Challenge to Startup Hype
The term “Anti-Entrepreneur” is deliberately provocative. It does not mean opposing entrepreneurship. Instead, Madhu uses it to challenge practices that can create the appearance of success without establishing the foundations of a sustainable business.
A company can grow revenue while losing money on every transaction. It can raise substantial capital without developing a defensible competitive advantage. It can report a higher valuation while becoming increasingly dependent on additional funding. Madhu’s philosophy calls for a different set of priorities: economic fundamentals, disciplined execution, transparent governance and preparedness for risk.
The framework draws inspiration from strategic principles associated with the Mahabharata, translating them into a contemporary business context.
1. Dharma Over Valuation: Put Business Integrity First
The first principle is that a company’s underlying economic and operational reality must take precedence over its headline valuation. In a business context, the analogy is to maintaining ethical standards, honouring commitments and making decisions consistent with the company’s long-term interests.
For a startup, this means building a product that solves a real problem, presenting financial information honestly and establishing a business model that can withstand scrutiny. Valuation matters, but it should reflect a credible assessment of the business rather than become a substitute for performance.
2. Karmanye Vadhikaraste: Execution Before Exit Fantasies
The second principle draws on the Bhagavad Gita’s teaching commonly expressed as focusing on one’s actions rather than becoming attached to their fruits. Madhu applies this idea to the daily discipline of building a company.
Founders can spend considerable time discussing future valuations, potential acquisitions or eventual stock-market listings. These ambitions may provide direction, but they cannot replace the work required to build a successful enterprise. Customer satisfaction, product quality, operating efficiency, cash management and employee performance are more immediate determinants of business health.
Execution is not a secondary activity undertaken after fundraising. It is the central mechanism through which business value is created.
3. Chakravyuha Preparedness: Understand the Risks Before Scaling
The third principle invokes the Mahabharata’s Chakravyuha episode as a metaphor for entering a complex environment without fully understanding how to navigate it or exit it. For startups, aggressive expansion can create a similar problem.
A business may enter multiple markets, hire rapidly or commit significant resources to expansion without understanding the associated financial and operational risks. Madhu’s framework emphasises identifying potential liquidity problems, assessing regulatory exposure, planning for changing market conditions and understanding the consequences of delayed fundraising.
A company should understand not only how it intends to grow but also what it will do if growth is slower than expected.
4. The Krishna Principle: Strategic Alliances and Mentorship
The fourth principle focuses on the importance of guidance, alliances and sound judgement. Applied to entrepreneurship, the analogy highlights the importance of choosing advisers, investors and partners who contribute meaningful strategic insight.
Capital alone does not automatically make an investor valuable to a startup. Founders may also need experienced mentors, potential customers, industry networks, technical expertise and guidance on governance. Effective mentorship should strengthen a founder’s judgement rather than replace it.
Together, these four principles create the philosophical foundation of Madhu’s Anti-Entrepreneur methodology: integrity, execution, preparedness and strategic wisdom.
The Investment Triangle: Technical, Management and Investment Discipline
Madhu’s second major framework is the Investment Triangle, which integrates three dimensions of venture development. The premise is that a startup becomes investment-ready when its technical capabilities, management systems and investment positioning are aligned.
The Technical Foundation
The first dimension examines whether the product or technology can solve a genuine problem and deliver reliable results. Key considerations include product performance, intellectual property, technical differentiation, operational feasibility and the ability to scale. A working prototype is not automatically a commercially viable product; investors must understand the gap between demonstration, deployment and scalable delivery.
Management and Governance
The second dimension focuses on the organisation responsible for turning technology into a business. This includes management capability, accountability, financial discipline, governance practices, unit economics and operational clarity. Strong governance helps founders understand their businesses, identify problems early and allocate resources effectively.
Investment Positioning
The third dimension concerns how a business presents its opportunity to potential investors and commercial partners. A credible investment proposition connects the company’s technology and operating model with its market opportunity, competitive advantage, financial projections and growth strategy.
The three dimensions are interdependent. Technological strength without management discipline can produce an inefficient business. Strong management without a differentiated product can limit growth. A compelling investment narrative without credible fundamentals may struggle under institutional due diligence.
Investment readiness, in this view, is not simply about preparing a pitch deck. It is about preparing the business itself.
From Investment Readiness to Enterprise Transformation
Madhu’s submitted profile describes his work with portfolio ventures as involving business-model refinement, new approaches to management, alignment with international benchmarks and stronger accountability.
A company preparing for institutional capital may need clearer financial reporting, stronger internal controls, improved performance measurement and evidence that its growth model is repeatable. It may also need to reconsider its customer segments, pricing strategy, product roadmap or organisational structure.
The transformation process differs by company. A manufacturing startup may prioritise production efficiency and supply-chain reliability, while a software company may focus on recurring revenue, customer retention and acquisition costs. A deep-tech venture may need technical validation and a credible path to commercial deployment before rapid expansion.
The relevant question is whether the operating model is appropriate to the company’s industry, development stage and strategic objectives. Investment readiness is about building the foundations of the business, not merely preparing a presentation.
Why India Is Becoming a Strategic Opportunity for Global Capital
Madhu views India as more than a market for consuming products or providing outsourced technical services. In his assessment, the country is increasingly positioned to develop products, build technology platforms and deliver capital-efficient innovation for global markets.
Digital Infrastructure and Entrepreneurial Scale
India’s digital public infrastructure, including UPI, creates opportunities for businesses to develop products and services around digital transactions and connected customer experiences. The wider technology ecosystem also supports innovation in enterprise software, financial services, logistics and digital commerce. Infrastructure alone does not guarantee commercial success; startups must still demonstrate customer demand, sound economics and the ability to compete.
Deep Technology and Strategic Sectors
India’s capabilities in defence, aerospace, unmanned aerial vehicles, medical technology and other engineering-intensive fields create opportunities for businesses combining technical expertise with disciplined capital deployment. These sectors can require patient investment, specialised talent, regulatory compliance and longer development timelines.
Cross-Border Business: India, MENA and Europe
Madhu’s experience across India, the Middle East and Europe informs his interest in cross-border business opportunities. Indian companies may serve overseas markets through technology exports, specialised engineering services, enterprise solutions and strategic partnerships. International expansion also requires understanding local regulations, procurement processes, customer expectations, distribution networks and competitive conditions.
Public Markets and Long-Term Investment Outcomes
India’s public markets can provide potential liquidity pathways for qualifying growth companies and their investors. However, an initial public offering is neither assured nor appropriate for every startup. Companies must build the scale, financial performance, governance and compliance systems needed to meet applicable listing requirements. Potential exits should follow from business development rather than become the sole reason for pursuing it.
The Authorial Dimension: Communicating Complex Ideas
Madhu’s professional profile identifies him as the author of SPARKS, Mayuram to Moscow: Billion Dollar Thread and Control Z. This writing experience adds another dimension to his professional identity.
Venture investing requires more than financial analysis. Investors must explain complex business ideas, communicate strategic priorities and help founders translate technical capabilities into a clear commercial proposition. Effective communication is especially important in deep technology, where the underlying science or engineering can be difficult for non-specialist decision-makers to evaluate.
A clear narrative can explain the problem, solution and commercial opportunity, but it must remain consistent with verifiable evidence. The objective is not to make a weak business sound compelling; it is to make a strong business understandable, credible and investable.
What Founders and Investors Can Learn from Madhu’s Approach
- Build substance before pursuing valuation. Demonstrate genuine customer value and a credible business model before relying on ambitious projections.
- Make execution measurable. Translate operational priorities into clear targets, responsibilities and performance indicators.
- Evaluate founders and markets together. Assess founder quality alongside customer demand, competition and business economics.
- Prepare for downside scenarios. Understand cash requirements, funding risks and options if expansion slows.
- Develop governance early. Transparent reporting, accountability and responsible management strengthen decision-making.
- Align technology with commercial reality. Product differentiation creates value when it solves a problem customers recognise and will pay to address.
- Treat capital as a responsibility. Funding should support measurable progress rather than merely extend the runway without addressing structural weaknesses.
The Road Ahead: Building Businesses That Can Withstand Scrutiny
The next phase of India’s startup development will require more than a steady flow of new ventures and investment announcements. It will depend on businesses that can establish durable customer relationships, develop defensible capabilities, maintain financial discipline and compete in domestic and international markets.
For investors, this creates an opportunity to contribute through rigorous evaluation, practical mentorship and a focus on sustainable enterprise value.
G. N. Madhu’s professional journey—from cross-border project leadership and his former executive role at Garuda Aerospace to venture architecture and serial startup investing—reflects this broader evolution in the relationship between capital and entrepreneurship.
His Anti-Entrepreneur philosophy challenges founders to question the pursuit of growth without adequate foundations. His Investment Triangle emphasises the need to align technical capability, management discipline and investment positioning.
The objective is not to build companies that merely appear successful during favourable market conditions. It is to help develop businesses capable of responding to competition, managing uncertainty and creating value over time.
In an ecosystem often captivated by the next funding round, Madhu’s central message is that the strongest investment proposition begins with the strength of the business itself.
About G. N. Madhu
G. N. Madhu is a venture architect, strategic investment professional and angel investor with a B.Tech, an MBA and more than two decades of cross-border professional experience spanning India, the Middle East and Europe. His experience includes project execution across energy, deep technology, defence and other sectors. He previously served as Chief Growth Officer and Investment Officer at Garuda Aerospace Limited and is now pursuing his work in startup investing and venture development.
He is also identified in his executive profile as the author of SPARKS, Mayuram to Moscow: Billion Dollar Thread and Control Z.